Roof insurance questions in Texas
Roof damage and insurance coverage involve different decisions. Understand the roles, gather the records and read the terms that apply to your policy.
Start with the policy and the condition
A roof inspection can help establish the physical condition and proposed work. It cannot promise that an insurer will cover the loss or pay for replacement. The policy, facts of the loss and insurer’s decision govern the claim.
Use this guide to organize questions for the insurer and the roofing contractor. It provides general Texas information, reviewed September 19, 2026, rather than a coverage decision for your property.
Roof scope and insurance coverage are different decisions
A roofing contractor cannot act as your public adjuster on a project where it is also doing the work.
Read these parts of the policy
Read TDI’s actual-cash-value and replacement-cost explanation and ask the insurer how those terms apply to your policy.
Keep the claim record organized
Document what changed
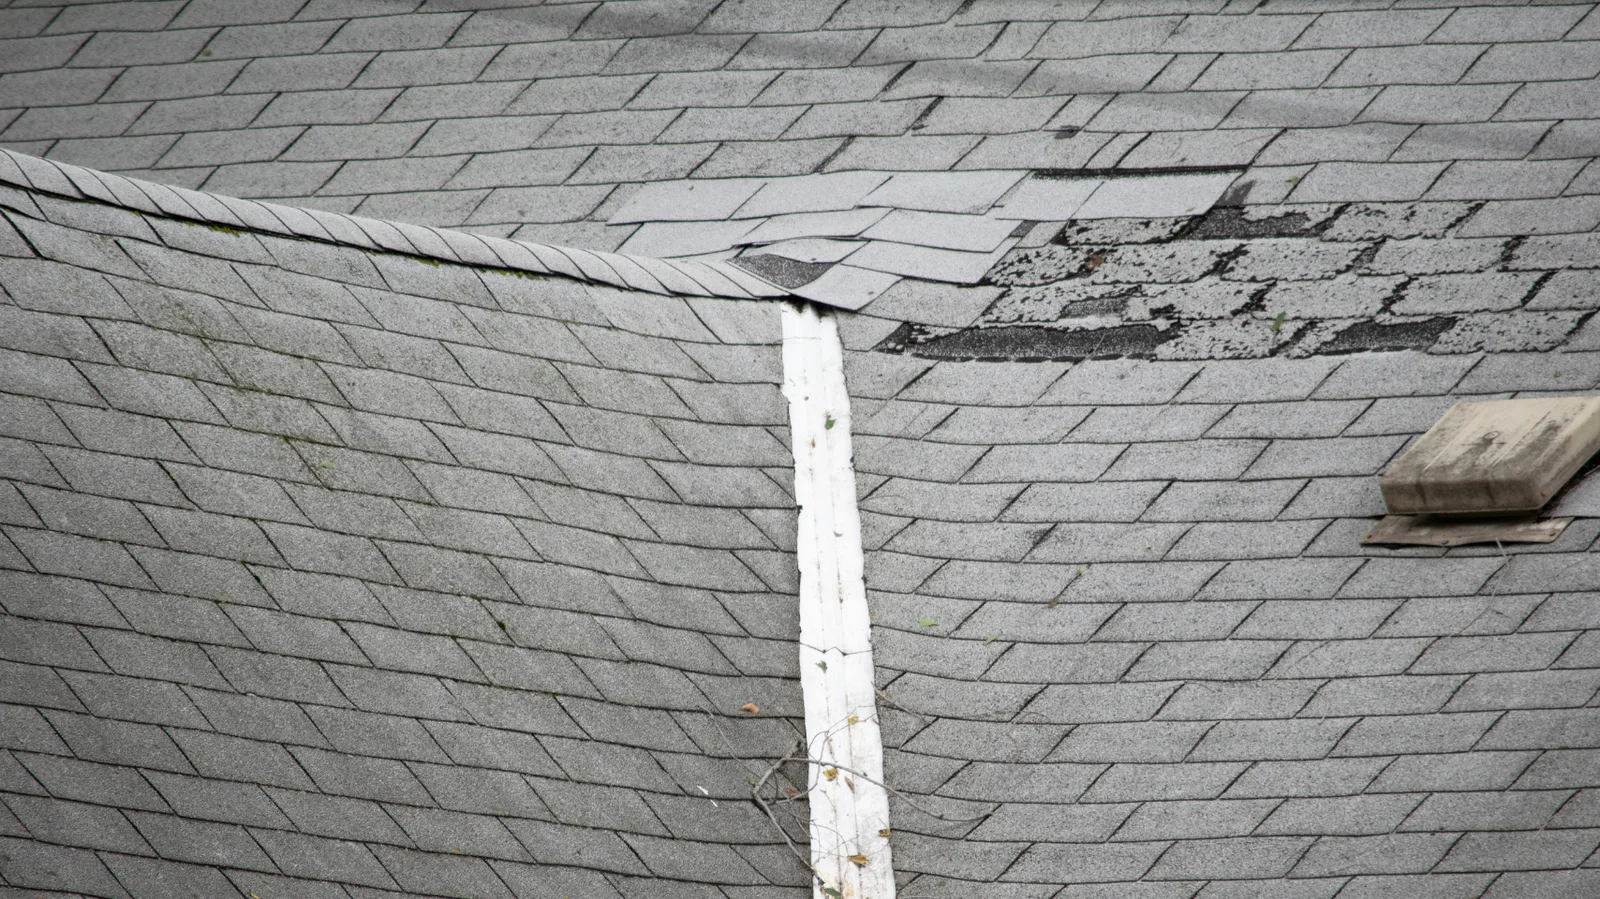
Keep dated photos taken safely, leak observations and the date of the weather event you are concerned about.
Retain the work record
Save inspection information, proposals, temporary-protection receipts and earlier roof records. Describe known prior damage accurately.
Ask about requirements
Contact the insurer about reporting deadlines, evidence, inspection and payment conditions. Keep its instructions with the claim record.
Texas does not allow deductible waivers
Texas Department of Insurance guidance states that contractors cannot offer to waive, rebate or absorb the property policyholder’s deductible. It also explains the prohibition on serving as contractor and public adjuster on the same project.
A roofing proposal should describe the actual work and price. Do not rely on an offer to make a deductible disappear, a promise of claim approval or a guarantee to recover a particular amount.
Roof claim questions
What if the contractor’s proposal differs from the insurance estimate?
First compare the work items and quantities so you understand the difference. Ask the contractor to explain its scope and ask the insurer about its coverage and payment decision. The contractor does not negotiate as your public adjuster on the same project.
Does hail reported nearby prove my claim?
Nearby storm reports provide context. They do not show the exact conditions or roof damage at your property, and they do not establish policy coverage.
Can an inspection distinguish wear from storm damage?
An inspection can identify observed conditions and the work being considered. Cause can require careful evaluation, and the insurer decides how the policy applies. Avoid treating every mark or old repair as proof of a new covered event.